RBI makes financial information easier to access for you: Account Aggregators to work across platforms, while fixed deposits will be visible in your CAS alongside stocks and mutual funds
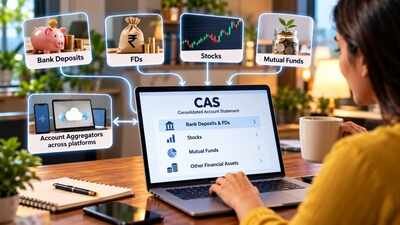
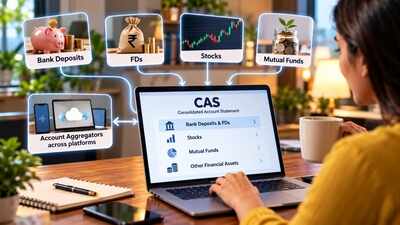
Soon, your Consolidated Account Statement (CAS) will reflect details from your mutual funds, insurance, banks and fixed deposits.The Reserve Bank of India (RBI) has enabled interoperability between account aggregators (AAs), a move that will allow customers to share their financial information more easily with different financial institutions, including banks, NPS fund managers, insurance companies and mutual funds.“With an objective to enhance customer convenience, it has been decided to implement interoperability among NBFC-Account Aggregators (NBFC-AA),” RBI said during the bi-monthly policy announcement by the governor.“This will enable customers to access and share their financial information, across different Financial Information Providers, through any NBFC-AA of their choice.”The central bank has also enabled depositories regulated by the Securities and Exchange Board of India (Sebi) to include information on bank deposit accounts in their Consolidated Account Statement (CAS) through NBFC-AAs.Also Read | After 3.5 years, RBI hikes repo rate: How does it impact your EMIs & loan interest payout? Explained
What the move means
For individuals who receive a CAS, this means information on their mutual funds, stocks and, going forward, fixed deposits (FDs) can be viewed together in one place.The change will allow demat account holders to see details of their demat holdings as well as bank deposit accounts together in a single CAS.Customers who do not hold demat accounts will also continue to have the option of accessing a consolidated view of their financial information and sharing it through NBFC-AAs, the RBI said.Both initiatives are aimed at making it more convenient for customers and are scheduled to be implemented by December 31.The RBI launched the Account Aggregator framework in September 2016. Account aggregators function as intermediaries connecting financial information providers, which hold customer data, with financial information users, such as lenders seeking access to that information after obtaining the customer’s consent.The Account Aggregator ecosystem covers entities regulated by the RBI, Sebi, Insurance Regulatory and Development Authority of India (IRDAI) and Pension Fund Regulatory and Development Authority of India (PFRDAI).CAS is prepared by depositories and registrar and share transfer agents (RTA) and provided to customers who have opted to receive them. Central Depository Services Limited (CDSL) and National Securities Depository Limited (NSDL) are the two depositories in India, while Karvy and CAMS are RTAs.Adhil Shetty, CEO, BankBazaar, told ET that a Consolidated Account Statement, or CAS, gives investors a single view of their securities holdings. Depositories such as NSDL and CDSL send CAS to investors who have demat accounts, covering holdings associated with their PAN.The CAS could serve a role similar to Form 26AS for income tax purposes. While Form 26AS brings together information relating to a taxpayer’s financial transactions, the expanded CAS will provide individuals with a consolidated view of their investment information.According to Vivek Iyer, Partner and Financial Services Risk Advisory Leader, Grant Thornton Bharat, the RBI’s move is an important step towards deepening India’s open finance ecosystem.“Interoperability among Account Aggregators should help reduce customer friction and complaints, prevent platform lock-ins, and improve data portability, allowing customers to access and share financial information through the Account Aggregator of their choice,” he says.Overall, these measures are likely to strengthen transparency, improve financial visibility for consumers, and further accelerate the adoption of India’s consent-based data-sharing framework.
- One view of net worth: Equity, mutual funds, NPS and deposits will be visible together. For a household holding FDs across three or four banks, this could provide a consolidated picture of asset allocation, including the amount held in debt.
- Nominee: The CAS currently indicates whether a nomination has been registered. Once FD details are included, investors will also be able to see whether a particular FD has a nominee. While the nominee does not become the owner of the FD, having a nominee can help the legal heir access the deposit, which is relevant for succession.
- Easier tax reconciliation: People may earn interest from deposits held across several banks, and such income can sometimes be under-reported. Having all deposits listed together can make it easier to compare the information with Form 26AS and the Annual Information Statement (AIS).
- Early warning of fraud: Any account or deposit that a customer does not recognise could become visible through a statement that the customer reviews.
At present, CAS covers investments held through the depository system as well as mutual fund folios. These include equity shares, mutual fund units, exchange traded funds, bonds, government securities and other securities maintained in demat form. The statement also contains transaction details and information on the value of holdings.